You can work hard all year and still have no money. You can earn a good salary and struggle to pay your bills. Worse, you may repeat the same struggle next year. The problem may not be your income alone. Your spending habits and money choices may also hold you back.
If you keep making the same mistakes, your finances may never improve. However, you can change your situation. You must first identify what drains your money. Then, you must take steps to fix those problems. In this article are 8 reasons you may remain broke this year, if you continue with the habit in this article that might have kept you broke last year.
1. You spend more money than you earn each month.
You cannot build wealth if you spend more than you earn. Even a good salary cannot protect you from this habit. For example, imagine you earn $3,000 each month but spend $3,200. You now face a $200 shortfall. If this continues, you may borrow money to cover your bills. Your next paycheck must then cover both new expenses and old debts. This leaves you with even less money.
To stop this cycle, compare your income with your monthly expenses. Include rent, food, transport, subscriptions, and other costs. Then, find expenses you can reduce. You may also need to change your lifestyle. If your income cannot cover your needs, look for ways to earn more. However, do not increase your spending when your income rises. Keep some of that extra money instead. Your goal is simple, spend less than you earn and keep the difference.
2. You do not have a clear plan for managing your income.
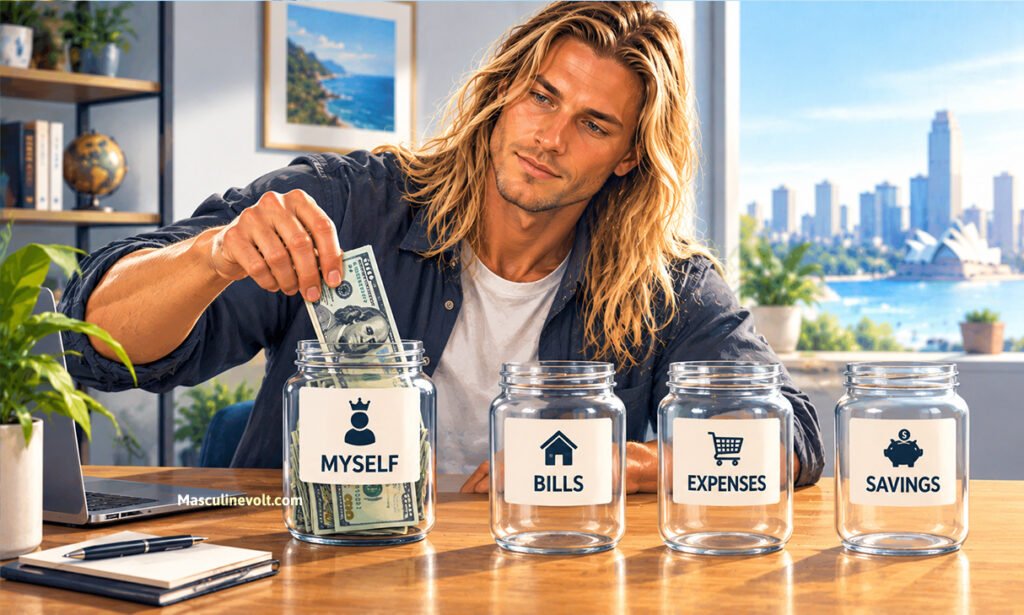
Money can disappear quickly when you spend without a plan. You may pay a few bills, buy things you want, and spend the rest. Soon, you may struggle to cover your basic needs. A budget helps you avoid this problem. It tells you how to use your money before you spend it. Start by writing down your monthly income and expenses. Then, set amounts for food, rent, transport, savings, and debt payments. Make sure your plan matches your actual income.
Do not create a budget based on money you hope to earn. According to research, adults who keep a budget report feeling more in control, more confident, and more secure with money. Meanwhile, 59 percent of the adults studied did not track their spending. That shows why a plan matters, since control starts with knowing your numbers. Also, check your spending every week. This helps you spot problems before they grow. If you spend too much in one area, adjust your habits. You do not need a complicated system to manage your money. A simple budget can help you make better choices. Give every part of your income a purpose. This way, you can control your spending and make steady progress toward your financial goals.
3. You waste money trying to impress other people.
Never try to impress people with your money. Such lifestyle can make you broke because you want others to think you are rich. You might buy expensive clothes, upgrade your phone, or visit costly places. You may even borrow money to maintain this image. However, people rarely see the financial stress behind your spending. They only see what you choose to show them. Social media can make this habit worse. You see people showing off their cars, trips, and expensive purchases. Then, you feel pressure to match their lifestyles. But you do not know their true financial situation. Some may earn more than you, while others may rely on debt.
According to research, about half of Americans overspent to impress others, and over half of those spenders fell into debt. Most of these spenders also regret the choice later. Showing off costs you twice, first in cash, then in regret. Stop using other people’s spending as your guide. Before buying something, ask yourself if you need it. Also, check whether you can afford it without hurting your finances. If a purchase will leave you short of money, delay it. You do not need expensive possessions to prove your worth. Focus on paying your bills, reducing debt, and building savings instead.
4. You depend on one source of income for too long.
You may struggle financially when you rely on one income source. If you lose your job, your bills will not stop. Your rent, food costs, and other expenses will still demand money. Even if you keep your job, your salary may not grow fast enough. Rising prices can also reduce what your income can buy. You can reduce this risk by exploring other ways to earn. Start with skills you already have. For example, you could tutor students, offer freelance services, or help local businesses.
Choose work that fits your schedule and abilities. Before you start, check the costs and risks. Avoid schemes that promise quick money without clear proof. You should also protect your main job while testing a new income source. Start small and learn what customers need. Then, improve your service as you gain experience. An extra income source can give you more financial options. However, you must manage that money wisely. Do not let a higher income push you into unnecessary spending.
5. You do not have savings to fall back on.
An unexpected bill can ruin your plans when you have no savings. According to research, only 63 percent of U.S. adults could cover a surprise $400 expense using cash or its equivalent. That leaves 37 percent of adults without a cash cushion for small emergencies. A small fund moves you into the safer group. Your car may need repairs, or you may face an urgent expense. You might also lose income for a short period. Without savings, you may borrow money or delay important payments. This can create more financial stress. You can reduce this risk by building an emergency fund.
Start with an amount you can afford to save regularly. You could move a small sum into savings whenever you receive your income. Keep this money separate from your daily spending funds. This makes it easier to avoid using it for unnecessary purchases. Set a small target first, such as saving enough to cover one urgent expense. Then, work toward a larger fund that covers several months of essential costs. Do not wait until you earn a large salary to start saving. Begin with what you can manage today. As your income grows, increase the amount you save. Your savings can help you handle problems without taking new loans.
6. You ignore the small expenses that drain your income.
Small purchases can take a large share of your income over time. You may buy snacks, order food, pay for unused subscriptions, or make frequent impulse purchases. Each expense may seem harmless on its own. However, these costs can add up over weeks and months. You may then wonder why your money never lasts.
The solution starts with tracking your spending. Write down every purchase for at least 30 days. Include cash payments, card purchases, and automatic charges. At the end of the month, review your list. Look for expenses you can cut or reduce. Cancel subscriptions you no longer use. Set a limit for optional purchases, too. However, you do not need to stop buying everything you enjoy. Instead, spend on things that matter to you. Cut costs that offer little value. You can then use that money to build savings or repay debt. When you track your spending, you see where your income goes. This gives you more control over your financial choices.
7. You fail to improve your skills to increase your value and earning power.
You may limit your income when you stop learning new skills. Working hard matters, but hard work does not always lead to higher pay. Employers and customers often pay more for skills that solve important problems. If you keep doing the same work, your earning options may remain limited. According to research, full-time workers without a high school diploma typically earned $770 weekly, while bachelor’s degree graduates earned $1,578. Unemployment also fell from 6.1 percent to 2.8 percent across those groups. Learning useful skills can raise your pay and protect your income.
Start by finding out which skills employers in your field need. If you run a business, look for skills that can attract more customers. Then, choose one skill you can learn and practice. You can use affordable courses, books, or free learning resources. However, research the demand before spending money on training. Do not pay for a course simply because someone promises high earnings. Choose skills that fit your goals and offer real value. Set aside time each week to improve. Then, apply what you learn at work or in your business. You could seek better jobs, request more responsibility, or offer new services. Building useful skills takes time. However, it can help you qualify for better opportunities and increase your earning power.
8. You make financial decisions without considering your future plans.
You may hurt your finances when you focus only on what you want today. You might buy an expensive phone without checking your other bills. You may also spend money that you planned to save. These choices can delay your goals and create financial stress. Before making a major purchase, check how it will affect your budget.
Ask yourself whether you can still pay your bills and meet your other needs. Also, think about your goals for the coming months and years. You may want to build an emergency fund, repay debt, or save for retirement. Write down these goals and set realistic targets. Then, use them to guide your spending. For example, you can delay a costly purchase until you save enough for it. This helps you avoid debt and protect your savings. You do not need to reject every enjoyable expense. Instead, understand what you give up when you spend. When you consider your future plans, you can enjoy today without damaging tomorrow.
Final Words
You may remain broke if you keep repeating the same financial mistakes. Spending too much, ignoring savings, and taking frequent loans can hold you back. However, you can change these habits. Start by tracking your expenses and creating a realistic budget. Then, reduce waste, build savings, and work on your earning skills.
You do not need to fix every problem today. Choose one habit to change and take action. Once you gain control over it, move to the next. Small changes can improve how you manage your money over time. Your income matters, but your choices matter too. Take control of your finances now, rather than waiting for a better year.
QUOTE OF THE ARTICLE