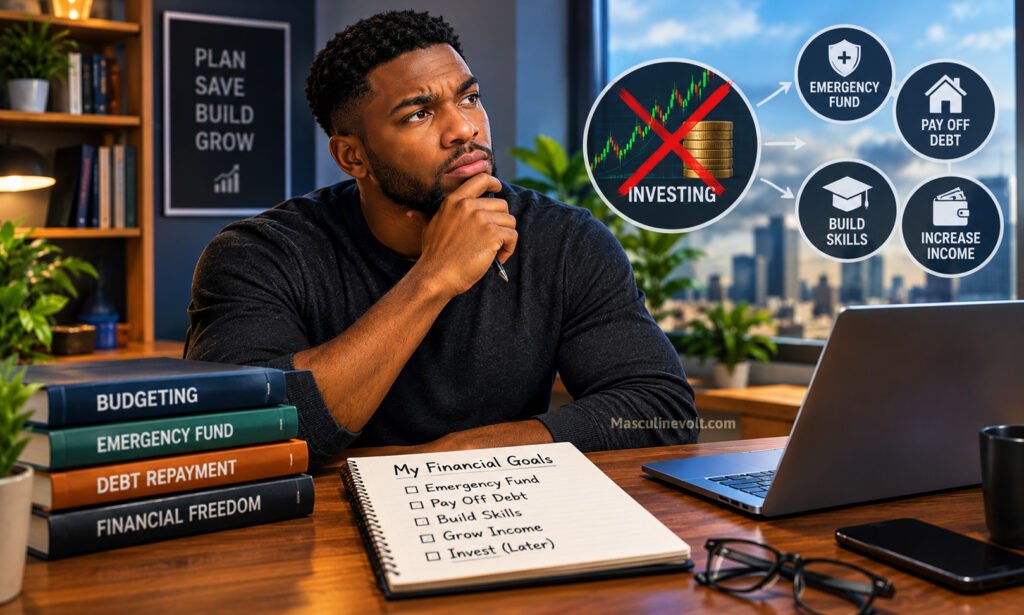
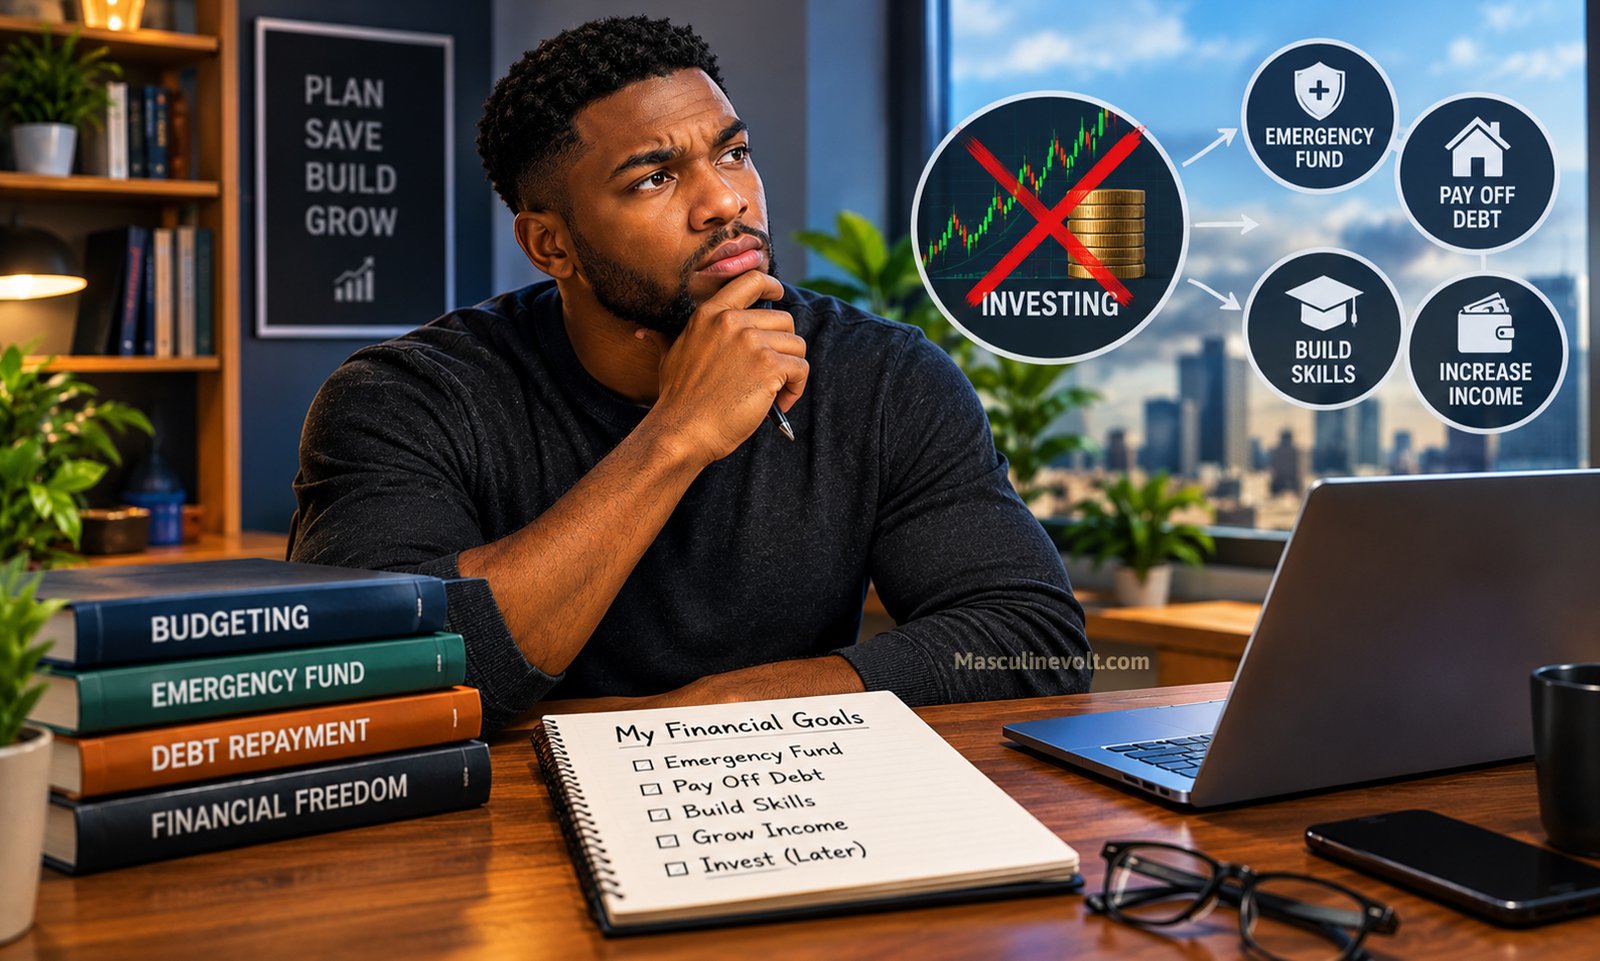
Investing can help you grow your money, but starting too soon can hurt your finances. You may buy stocks today, then sell them tomorrow to pay rent. You may also lose money because an emergency forces you to withdraw your investment. These problems can slow your progress before you gain real benefits. Therefore, you should prepare your finances before putting money into assets.
You do not need to become rich before you start investing. However, you need a strong base that supports your daily needs and future plans. This article highlighted financial targets you should work toward before you start investing.
1. Build an Emergency Fund Before Investing
Your emergency fund should protect you when life brings unexpected costs. For example, your car may break down, or you may need urgent medical care. Without savings, you might sell your investments at the wrong time. You could also take a loan and pay extra interest. An emergency fund helps you avoid these problems. According to research, adults who say they do not save are nearly three times more likely to struggle paying bills. More than half of people report holding $3,000 or less across checking and savings. Saving first gives you a buffer before you invest.
Start by saving enough to cover one urgent expense. Then, work toward three to six months of essential living costs. Your target may depend on your job security, family needs, and regular expenses. If your income changes often, you may need a larger reserve. Keep this money in an account you can access quickly. Do not place it in risky assets or lock it away for long periods. Your emergency fund serves a different purpose from your investments. It protects your financial stability, while investments aim to grow your money over time.
2. Pay Off High-Interest Debt Before Buying Assets
High-interest debt can make it harder to grow your wealth. Credit cards and some personal loans charge interest that can exceed your investment returns. According to research, credit card accounts that were charged interest averaged an annual rate of about 22 percent in 2025. Even the average cost of card debt can outrun the gains you expect. That makes debt payoff a smart first goal. For example, your investment might earn 7% in a year, while your debt charges 20%. Your investment gains may not cover the cost of that debt. As a result, your overall financial position could get worse.
Start by listing your debts and their interest rates. Continue making the required minimum payments on every debt. Then, direct extra money toward the debt with the highest interest rate. This approach can reduce the interest you pay over time. You do not always need to clear every debt before investing. Low-interest loans with manageable payments may fit your wider financial plan. However, deal with costly debt before taking major investment risks. Once you reduce that burden, you can use more of your income to build assets and improve your financial position.
3. Create a Stable Income Before Taking Investment Risks
Your income affects how much risk you can afford to take. If you struggle to earn enough for your basic needs, investing may add pressure. You might depend on investment gains to pay your bills. However, markets do not provide steady returns every month. Some investments can lose value when you need money most. Therefore, aim for a reliable way to cover your regular expenses. This could come from a job, a business, or several dependable sources.
You do not need a perfect income before you start investing. Instead, make sure you can meet your main needs without relying on investment profits. If you work for yourself, review your income across several months. This helps you understand how much money you can safely set aside. According to research, 30 percent of adults had varying income, and 11 percent struggled to pay bills because of it. Among self-employed adults, 58 percent said their income varied from month to month. Uneven pay can break an investment plan fast. You should also plan for periods when earnings fall. A stable income gives you room to handle market changes without making rushed decisions. It also helps you invest for long-term goals rather than immediate survival.
4. Cover Basic Living Expenses Before Investing
You should be able to afford your basic needs before committing money to investments. These needs include housing, food, utilities, transport, and essential healthcare. If you cannot cover them, investing may create more problems than benefits. You might need to sell your assets to buy groceries or pay rent. That can interrupt your investment plan and cause losses. Start by calculating how much you need each month to live.
Use real costs rather than rough guesses. Include regular bills and necessary expenses that occur only a few times each year. Then, compare that total with your reliable income. If your income falls short, focus on closing the gap. You may need to reduce certain costs, increase your earnings, or adjust your living arrangements. Once you can cover your basic needs, review what remains. Only consider investing money that you can leave untouched for the period your plan requires. This gives you a better chance of staying invested when unexpected costs arise.
5. Build a Budget That Controls Your Spending
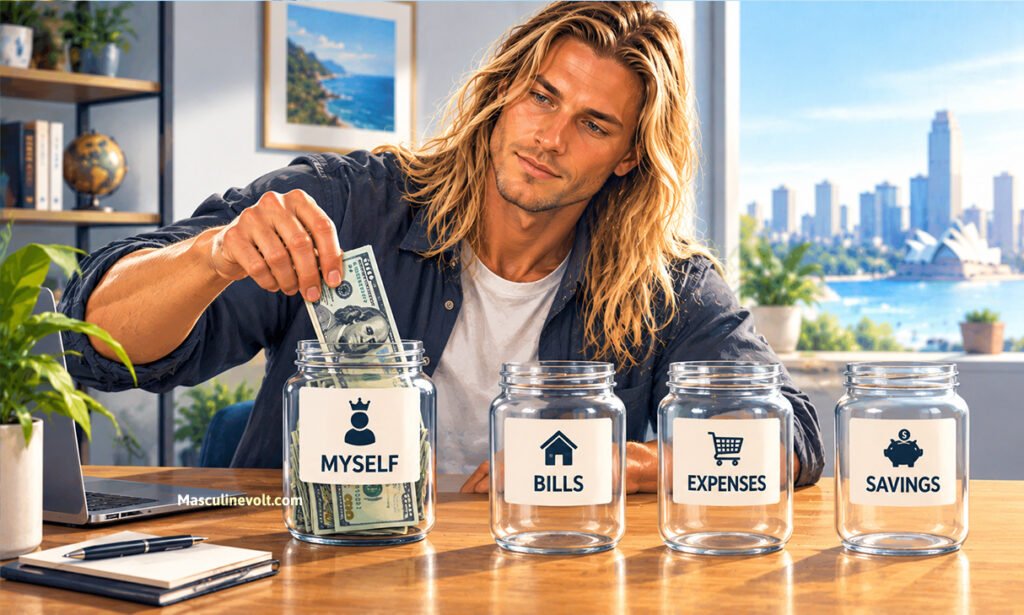
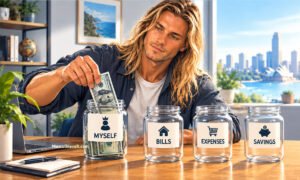
A budget helps you decide how much money you can invest without harming other goals. Without one, you may invest too much after payday and struggle before your next paycheck. You might also underestimate bills that arrive every few months. To avoid these problems, divide your income among essential expenses, debt payments, savings, and personal spending. Include annual costs, such as insurance renewals or vehicle maintenance, where they apply.
Set aside money for these expenses before they arrive. Then, identify an amount you can invest regularly without stretching your finances. Your budget should reflect your real habits and needs. Do not copy another person’s plan if your income and expenses differ. Review your spending each month and adjust the figures when your situation changes. You can start with a small investment amount and increase it as your finances improve. A good budget does more than limit spending. It shows you what you can afford to invest while keeping your other financial goals on track.
6. Secure Your Financial Position Before Chasing Returns
High returns may attract your attention, but they should not guide every financial decision. Some investments offer the chance to earn more because they also carry greater risk. If you put too much money into one risky asset, a loss could damage your finances. Therefore, focus on financial stability before chasing large gains. Check whether you have enough cash for urgent needs and whether your debts remain manageable.
Consider how a drop in investment value would affect your plans. If losing the money would threaten your housing, food, or other essential needs, you should not risk it. You should also avoid using borrowed money to chase investment profits. Instead, set clear limits on how much money you can expose to risk. Learn how different assets behave and understand what could cause losses. Do not trust promises of guaranteed high returns. Every investment carries some form of risk, and higher returns are never certain. Protecting your financial position helps you make calmer choices and handle setbacks without losing control of your wider finances.
7. Learn Basic Money Management Before Choosing Investments
You should understand how to manage money before deciding where to invest it. Otherwise, you may choose an asset without knowing how it fits your needs. According to research, only 27 percent of U.S. adults answered at least five of seven everyday financial knowledge questions correctly. Only 58 percent knew how inflation reduces what savings can buy. Learning the basics first helps you avoid costly guesses. Start by learning how income, expenses, savings, debt, and interest affect your finances. Then, learn the basic features of common investments, such as stocks, bonds, and funds.
Find out how each asset can gain or lose value. You should also understand investment fees, taxes, and the time you may need to reach your goals. These details can affect how much money you keep. Avoid buying an investment just because a friend recommends it or a social media post praises it. Instead, research how it works and what risks it carries. Make sure you can explain why the investment suits your goals. You do not need expert knowledge before you begin. However, you should understand what you are buying and what could go wrong. Basic financial knowledge can help you avoid poor choices and spot warning signs before you commit your money.
8. Protect Yourself Against Unexpected Financial Emergencies
An emergency fund covers unexpected costs, but other forms of protection may also matter. For example, suitable health, home, or vehicle insurance can reduce the financial impact of certain events. The right cover depends on your location, family needs, and personal risks. Without suitable protection, one major event could force you to use savings or sell investments. Start by reviewing the risks that could cause serious financial harm. Check which risks your current insurance covers and which ones it leaves out. Read the terms, limits, exclusions, and costs before choosing a policy.
Do not pay for cover you do not need, but avoid ignoring major risks just to save money. According to research, 59 percent of adults faced a major unexpected expense in one year, often costing $1,000 or more. Uninsured adults were nearly twice as likely to skip care because of cost. Good cover keeps one bad event from draining your investments. You should also keep important financial records safe and make sure you can access your accounts. If you support family members, consider how they would manage if your income stopped. These steps can help protect the money you work hard to earn. Once you reduce major financial risks, you may find it easier to follow your investment plan during difficult periods.
9. Know When You Are Financially Ready to Start Investing
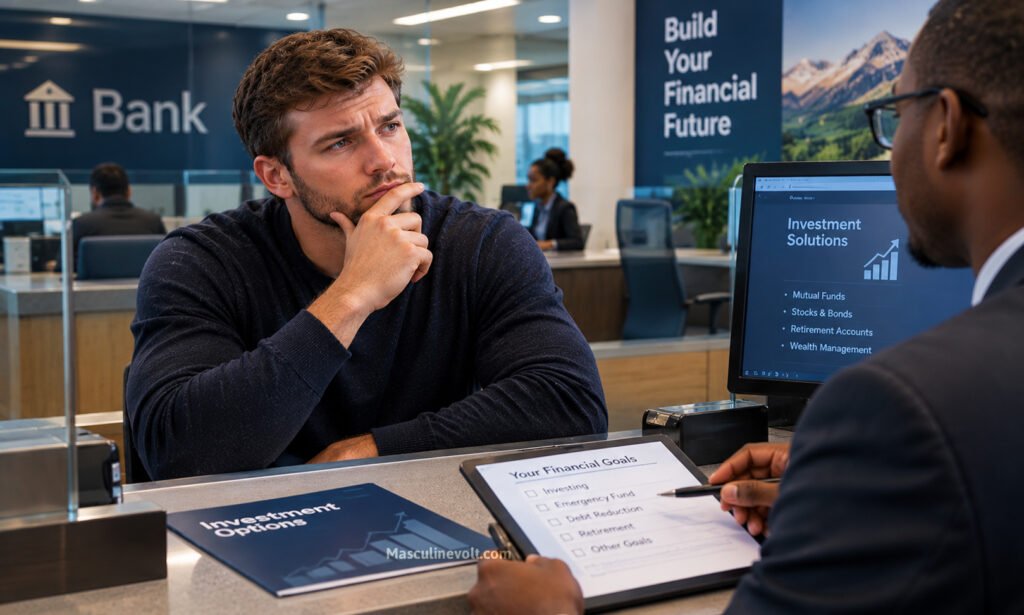
You do not need to meet every financial goal perfectly before you begin investing. However, you should know whether your current situation can support it. Start by checking your monthly cash flow. Can you pay your essential bills without borrowing money? Do you have some emergency savings? Can you manage your high-interest debt? These questions can help you judge your readiness. Next, identify your investment goal and the time you have to reach it. Money for a goal next year may need a different approach from money for retirement decades away. Then, decide how much you can invest without affecting your basic needs.
Start with an amount that fits your budget, even if it seems small. Choose investments you understand and research their risks before committing money. You should also plan how often you will review your investments. If you still struggle to cover essential expenses, work on that problem first. The right time to invest comes when you can accept the risks without putting your financial stability in danger.
Conclusion
Investing can help you build wealth, but preparation matters. You need a plan that protects your basic needs and supports your long-term goals. Build emergency savings, manage costly debt, and make sure your income covers your expenses. Learn how to budget and understand the risks before choosing investments. You should also protect yourself against financial setbacks that could force you to sell your assets too soon. Remember, you do not need perfect finances before you begin. You need a realistic plan and enough stability to follow it. Start by improving the area that needs the most attention. Then, invest when your money can support both your present needs and future goals.
QUOTE OF THE ARTICLE